

Albert: Budgeting and Banking
by Albert - Budgeting & Banking
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
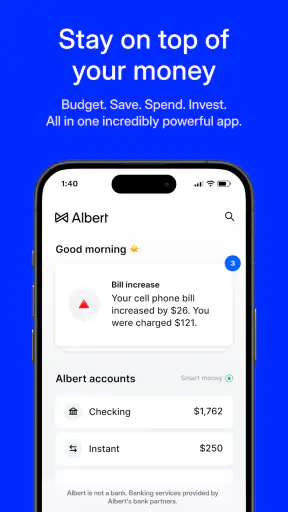
Managing money usually becomes difficult at the exact moment life gets busy. Bills arrive on different days, subscriptions quietly renew, and a reasonable spending plan can disappear after a few unplanned purchases. I found that Albert: Budgeting and Banking is most interesting when viewed as a practical budgeting companion rather than as a complete replacement for every financial service. Its central value is bringing everyday money decisions into one place so I can see what is happening before a small mistake turns into a stressful week.
Albert is a free finance app from Albert - Budgeting & Banking, available for everyone and compatible with Android devices running version 7.0 or later. It has built a substantial audience, with over ten million installs, around one hundred sixty thousand ratings, and a 4.5 average. Those figures suggest that the app has become a familiar option for people who want help organizing spending, saving, banking, and investing without starting with a complicated spreadsheet.
Why Albert’s budgeting view matters more than another account screen
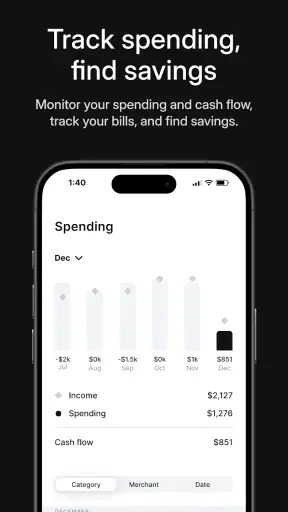
The capability I found most useful is the way Albert turns scattered financial activity into a budgeting routine. A normal banking app is primarily designed to show balances and transactions. That is helpful, but it often leaves me to interpret what those numbers mean. Albert’s appeal is that it encourages me to look at money as a flow: what is available, what needs to be reserved, and what can safely be used for ordinary spending.
That distinction matters. Seeing a healthy account balance can be misleading when rent, utilities, or a card payment are still waiting in the background. A budgeting-focused app is valuable when it helps separate “money I have” from “money I can actually spend.” In my experience, that is a more useful question than simply checking whether the balance looks positive.
The app also brings budgeting together with banking, saving, and investing. I would not treat that combination as a reason to use every part automatically. Instead, I see it as a way to reduce the number of places I need to check when making a basic financial decision. Someone who wants a single financial dashboard may appreciate that approach, while someone who prefers highly specialized tools may find it less focused than separate apps.
The biggest practical benefit is not a prettier balance screen; it is the pause before spending. When I check the broader picture first, I am less likely to mistake temporary cash availability for spare money. That small change in behavior can be more important than any individual budgeting label.
Turning a monthly plan into a weekly decision
Many budgets fail because they are written once and forgotten. Albert works better when I use it as a quick checkpoint throughout the month. Instead of asking whether I am following a perfect category limit, I can ask whether today’s purchase fits alongside the obligations that are still ahead.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is especially useful for people with uneven income or irregular expenses. A fixed monthly plan can feel unrealistic when pay arrives at different times or when groceries, transport, and household costs change from week to week. The app does not remove that uncertainty, but it gives me a place to notice it sooner and adjust my behavior before the end of the month.
I also like the idea of using a budget as a conversation starter with myself rather than as a punishment system. If I spend more than expected in one area, the useful response is to understand why and compensate deliberately elsewhere. The app is best suited to that kind of ongoing awareness. It is less suitable for someone who wants a detailed accounting system with extensive manual controls and precise forecasting.
How I would use it in everyday life
My recommended setup would begin with observation rather than immediate optimization. I would first review the transactions and recurring obligations that appear, then compare them with the way I actually spend. This exposes the common problem of building a budget around intentions instead of habits. A plan based on real behavior is usually easier to maintain than one based on an ideal version of the month.
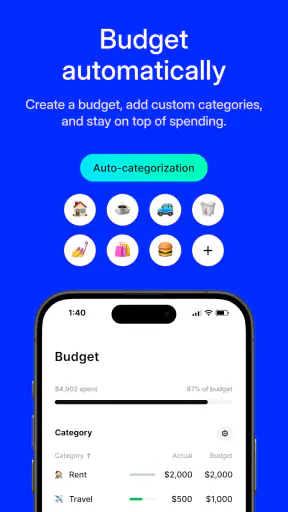
After that, I would choose a small number of spending priorities. I would not try to create an elaborate category for every type of purchase on the first day. The more useful early goal is to identify the expenses that can disrupt the month: housing, food, transport, debt payments, and recurring services. Once those are understood, smaller adjustments become easier.
A realistic example would be a person paid twice a month who checks Albert before a weekend of ordinary spending. The account balance may look comfortable, but the person also knows that several fixed payments are due before the next payday. Rather than treating the whole balance as available, they use the budgeting view to decide what portion can safely cover groceries, a social plan, and fuel. The app does not make the decision for them; it makes the decision harder to ignore.
That workflow is more valuable than opening the app only after overspending has already happened. I would check it before large discretionary purchases, after an unusually expensive week, and whenever income changes. Those moments provide the clearest benefit because they turn the app into a planning tool instead of a record of past mistakes.
A useful routine for saving without making the budget fragile
Saving is often presented as an amount to set aside immediately, but the timing can matter just as much as the amount. I would use Albert’s saving side only after making sure the everyday budget remains realistic. Moving money away too aggressively can create a false sense of progress if I later need to pull it back for basic expenses.
A better approach is to connect saving with a specific purpose, such as a buffer for irregular bills or a planned purchase. That makes the decision easier to evaluate. If the saving goal competes with rent or food, it is too ambitious. If it is small enough to survive an ordinary month, it has a better chance of becoming a habit.
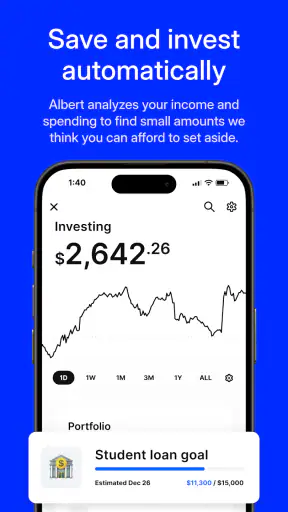
The same caution applies to investing. Having investing available inside a finance app can be convenient, but convenience should not be confused with suitability. I would treat investing as a separate decision from budgeting and saving, because money needed soon should not be exposed to the same uncertainty as long-term funds. Albert can bring these topics together, but I still need to keep their purposes distinct.
Where the all-in-one design helps
The combined design is strongest for someone who is tired of switching between a bank app, a notes file, a savings tool, and a separate place for investments. A single overview can make financial maintenance feel less like administration. It is also easier to build a regular checking habit when the relevant information is gathered in one familiar app.
That convenience has a behavioral effect. Every extra tool creates another reason to postpone reviewing money. If Albert reduces that friction, it may help a person act earlier and more consistently. I consider this a real advantage, especially for users who are not interested in building a detailed spreadsheet or learning a complex financial platform.
However, the all-in-one approach can also encourage shallow reviews. Seeing banking, saving, and investing together may make them look equally simple, even though they involve different decisions and levels of risk. I would use the unified view for awareness, then slow down whenever the choice involves moving money, committing to a financial product, or accepting investment risk.
The trade-offs I noticed before recommending it
Albert is not a magic solution for people whose income is too low for their essential expenses. A budgeting app can reveal the gap, help prioritize payments, and make spending patterns clearer, but it cannot create money. Users facing serious financial pressure may need debt counseling, direct negotiation with providers, or a more hands-on plan than an app can offer.
It may also feel limiting to people who want complete manual control. Spreadsheet users often enjoy designing their own categories, formulas, forecasts, and reports. Albert’s strength is reducing that workload, so its approach may feel restrictive to someone who wants to inspect every assumption or build a custom financial model.
There is another trade-off in relying on a connected financial overview: I would still verify important transactions and balances against the relevant account before making a major payment or transfer. An app can be an excellent planning layer, but I would not use any budgeting display as the only authority for time-sensitive financial commitments.
Privacy and trust also deserve a deliberate decision. A finance app is not a casual entertainment download; it becomes part of how I understand sensitive money information. Before using it deeply, I would read the current terms, security explanations, and connection details shown during setup. That is not a criticism unique to Albert. It is simply the standard I apply to any service handling financial data.
People should also consider whether they want banking and investing in the same experience. Some users will enjoy the convenience, while others will prefer to keep their primary banking relationship separate from budgeting software and use a dedicated investment platform for research and control. Neither preference is automatically better. It depends on whether simplicity or specialization is the priority.
How it compares with familiar alternatives
Compared with a traditional bank app, Albert is more useful for interpreting spending than for merely displaying an account balance. A bank app remains the natural place to confirm core account activity, while Albert can serve as the broader planning layer. I would use them together rather than assuming one must replace the other.
Compared with a spreadsheet, Albert requires less manual maintenance and is easier to check during a busy day. A spreadsheet wins when I need custom formulas, unusual categories, or a long historical record arranged exactly my way. The choice is therefore less about which tool is universally superior and more about whether I will actually keep the system updated.
Compared with a dedicated investing app, Albert is likely more appealing to someone who wants investing alongside everyday financial organization rather than deep market research. A specialist platform may be better for a user who wants more investment-focused detail. Albert’s advantage is the context: investment decisions appear beside the budget and savings picture, which can encourage more responsible separation between short-term needs and long-term goals.
Compared with using separate savings and budgeting apps, Albert offers less fragmentation. That can make a routine easier, but it also means I would need to be comfortable with one developer, Albert - Budgeting & Banking, covering several financial functions. For a person who values a carefully chosen specialist for each task, separate services may still feel more appropriate.
Who gets the most from Albert
I would recommend Albert most strongly to someone who has income coming in regularly but feels unsure where it goes. That person does not necessarily need an advanced financial system. They need a clear moment of review before spending, a way to think about upcoming obligations, and enough structure to make saving less accidental.
It can also suit a newcomer to budgeting who finds spreadsheets intimidating. The free price removes an initial financial barrier, and the Everyone age rating makes the app broadly approachable. Still, free does not mean effortless: the user must review the information, question the plan, and make the final choices. The app can organize attention, but it cannot replace judgment.
Albert is less convincing for a professional budget analyst, a household that needs detailed shared accounting, or an investor seeking specialized research tools. It may also disappoint anyone hoping for a completely automatic path to financial stability. The best results come from using it regularly and treating its suggestions or summaries as prompts for decisions rather than unquestionable instructions.
For a household, I would begin by agreeing on the few financial questions the app should answer: how much is safe for ordinary spending, which bills are approaching, and what amount can be saved without causing a shortfall. That keeps the tool practical. Trying to make it represent every financial detail immediately can turn a helpful overview into another chore.
What I would check before making it a daily tool
I would first confirm that the app supports my device, since the listed minimum is Android 7.0 or later. I would then spend time reviewing the setup screens and the way accounts, transactions, and financial sections are presented. The first impression matters less than whether I can understand the picture quickly without second-guessing every number.
I would also decide in advance what I want the app to accomplish. If the goal is to stop overspending between paydays, I would focus on available spending and upcoming obligations. If the goal is building a buffer, I would evaluate saving separately. If the goal is investing, I would avoid letting the presence of that feature distract from basic cash-flow stability.
Finally, I would create a routine that takes only a few minutes at a meaningful point in the week. The most useful check is usually before spending decisions, not after. I would look for unusual transactions, compare the remaining money with upcoming needs, and adjust one behavior rather than attempting a complete financial overhaul every time.
My overall view is positive, with an important qualification: Albert works best as a behavioral budgeting tool wrapped around broader financial features. Its value comes from making the question “what can I safely spend?” more visible and more frequent. That is a modest capability, but it addresses a real everyday problem.
My recommendation is to try it if you want less financial clutter and a clearer spending routine, but keep specialized tools or direct account checks where you need deeper control. The current version, 10.0.64, reflects an actively maintained app experience, and its large user base makes it an established choice rather than an obscure experiment. I would not expect it to solve complex financial situations on its own, yet for a person who needs a simple, repeatable way to connect budgeting with saving and banking, it can become a genuinely useful part of the week.
Pros
- Clear spending categories make it easy to track where your money goes.
- Automatic transaction syncing reduces the need for manual expense entries.
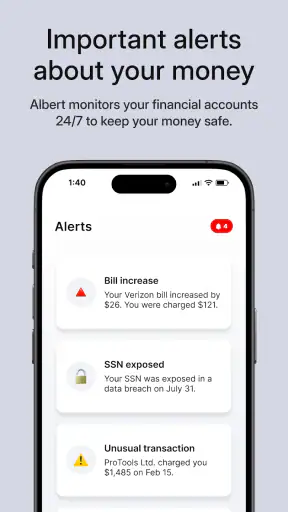
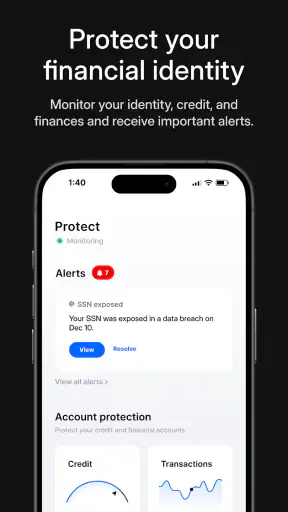
- Helpful alerts can warn you about upcoming bills and unusual spending.
- Budget tools are simple enough for beginners to understand quickly.
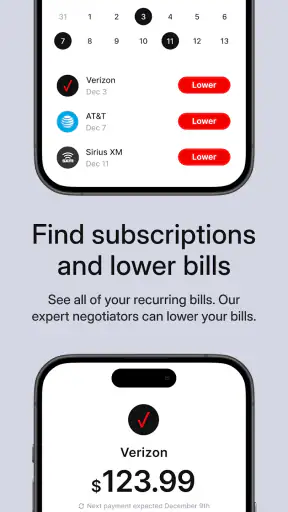
- Useful insights encourage more consistent saving and financial planning.
Cons
- Some features may require linking supported bank accounts or financial services.
- Bank synchronization can occasionally fail or take time to update.
- Advanced budgeting controls may feel limited for experienced users.
- Financial data access may raise privacy concerns for cautious users.
- The app may not support every bank, card, or regional financial institution.
FAQs for Albert: Budgeting and Banking
What is Albert: Budgeting and Banking, and what can I use it for?
Albert: Budgeting and Banking is a personal finance app designed to help you manage spending, organize money, monitor bills, and build healthier financial habits from one place. Depending on your eligibility and location, it may offer banking features, savings tools, budgeting insights, cash advances, and other financial services. Available features can vary, so review the current terms before signing up.
Is Albert: Budgeting and Banking a real bank, and is my money protected?
Albert provides banking-related services through partner financial institutions rather than operating like a traditional bank in every respect. Eligible funds may receive protection through the program bank and applicable deposit insurance rules, but coverage depends on how the account is structured and the current terms. Read the account agreement carefully, especially regarding insurance, access, and account limitations.
Does Albert charge fees or require a subscription?
Albert may offer a combination of free tools and paid membership features, depending on the plan selected and the services you use. Some optional products may involve fees, expedited-transfer charges, or other costs. Before confirming registration, check the latest pricing information in the app, including recurring membership charges, cancellation rules, and any conditions attached to advances or other financial services.
Can Albert help me save money or create a budget automatically?
The app is designed to analyze connected financial activity and provide spending insights, savings recommendations, and budgeting guidance. It may help identify recurring expenses, categorize transactions, and move money toward savings according to your preferences or eligibility. However, automatic recommendations are not a substitute for reviewing your finances yourself, and results depend on accurate account connections and transaction data.
What information does Albert require, and is it safe to connect my bank accounts?
To provide personalized financial features, Albert may request identity details, income information, contact data, and permission to connect external bank accounts. Financial apps commonly use encryption, authentication controls, and third-party connection services, but no online service is completely risk-free. Use a strong password, enable available security options, review permissions, and download the app only from an official store.

Albert: Budgeting and Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@albert.com, visit https://albert.com/, or review their https://albert.com/privacy/.










